How Household Budget Pressure Changes Spending Priorities
Introduction: A New Era of Everyday Economics?
Across the United States and much of the world, households are relearning the fundamentals of money management under pressure that feels both familiar and unprecedented. After years of elevated inflation, shifting interest rates, and rapid technological change, families are reordering what matters most in their monthly budgets, often in ways that reveal deeper changes in values, expectations, and long-term plans. For online visitors here this is not just an abstract economic story; it is a lived experience that connects the national economy, local job markets, and global financial trends to the most intimate decisions made around the kitchen table.
Economic data from organizations such as the U.S. Bureau of Labor Statistics and the Federal Reserve indicate that, although headline inflation has eased from its recent peaks, cumulative price increases over the last several years have reset the baseline cost of essentials such as housing, food, transportation, and healthcare. At the same time, wage growth has been uneven across sectors and regions, leaving many households feeling that their paychecks do not stretch as far as they once did. As a result, spending priorities are shifting in ways that are reshaping retail patterns, financial services, and even the broader structure of the economy.
This article explores how budget pressure is changing what households choose to spend on, how they think about debt and savings, and how businesses, policymakers, and communities are responding. Drawing on recent research from sources including the Federal Reserve, the Pew Research Center, the OECD, and McKinsey & Company, and connecting these insights to the editorial focus on this site, it examines not only the challenges but also the adaptive strategies and positive innovations emerging from this period of financial strain.
Clever individuals who wish to follow related daily events in macroeconomic trends and policy responses can find further reporting at the economy section at usa-update.com/economy and the latest headlines in the news hub at usa-update.com/news.
The Macroeconomic Backdrop: Why Budgets Feel Tighter
Household spending decisions do not occur in a vacuum; they reflect the interaction between personal circumstances and broader economic forces. Over the past several years, consumers in the United States and other advanced economies have navigated a sequence of shocks: pandemic disruptions, supply chain bottlenecks, surging inflation, and a rapid tightening of monetary policy. Analysts at the International Monetary Fund and World Bank have documented how these forces have combined to raise living costs and reshape labor markets in ways that are still playing out.
For many families, the most visible manifestation of this shift has been the persistent elevation of prices in core categories such as shelter, groceries, and utilities. Even as inflation rates have moderated from their peaks, the cumulative effect means that the baseline cost of essential goods and services remains significantly higher than in the pre-pandemic era. The U.S. Bureau of Labor Statistics provides detailed breakdowns of these trends in its Consumer Price Index data, showing that categories like rent, homeowners' equivalent rent, and certain food items have outpaced overall inflation for sustained periods.
At the same time, central banks, including the Federal Reserve, have raised interest rates to combat inflation, affecting mortgage costs, credit card rates, auto loans, and business borrowing. The Federal Reserve's consumer credit statistics and household surveys indicate that many families now face higher debt servicing costs, which directly reduce the amount of disposable income available for other expenditures. In its periodic Survey of Household Economics and Decisionmaking, the Federal Reserve has highlighted the growing share of households reporting that they are worse off financially than a year earlier, a sentiment that tends to correlate with increased budget pressure and more cautious spending behavior.
Globally, organizations such as the OECD have noted similar patterns in advanced economies from Europe to Asia, with households adjusting to what some analysts describe as a "higher-for-longer" cost environment. This context is crucial for understanding why consumers are rethinking their priorities, even in regions where employment levels remain relatively strong and headline economic growth has not collapsed. For readers interested in the intersection of macro trends and personal finance, our expert finance coverage at usa-update.com/finance offers continuing analysis of interest rates, inflation, and household debt dynamics.
The New Hierarchy of Needs: Essentials Take Center Stage
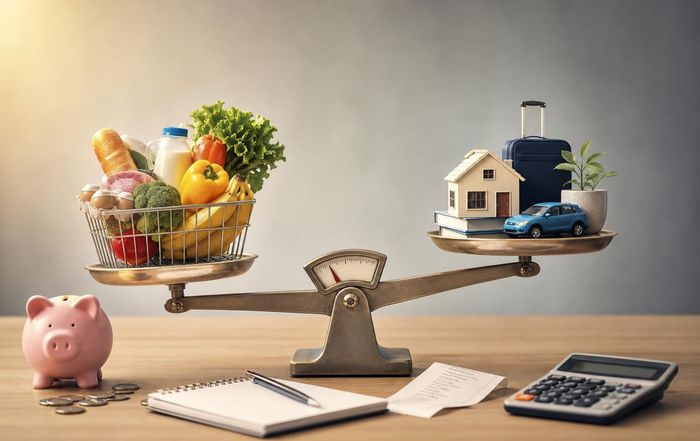
When budgets come under strain, spending naturally gravitates toward what households consider essential. Yet what counts as "essential" is not static; it evolves with technology, social norms, and the structure of modern life. Under today's pressures, many families are reaffirming a core hierarchy of needs while also integrating new necessities that did not exist a generation ago.
Housing, food, utilities, transportation, and healthcare remain at the top of the list. Surveys from the Pew Research Center and the U.S. Census Bureau show that rent or mortgage payments typically account for the largest single expense, followed by food and transportation. Rising rents in many metropolitan areas, combined with higher mortgage rates, have pushed some households to downsize, relocate to more affordable regions, or delay homeownership altogether. These choices have ripple effects on local economies, commuting patterns, and community life, topics that we continues to follow in the often cited business and jobs sections.
Food spending has also been reshaped. According to data from the U.S. Department of Agriculture's Economic Research Service, food-at-home prices rose significantly during recent inflationary periods, prompting consumers to trade down from premium brands to private labels, reduce discretionary items, and increase home cooking. Reports from research firms such as NielsenIQ and McKinsey & Company indicate that shoppers are more likely to compare prices, use digital coupons, and shift between retailers in search of better deals. The growth of warehouse clubs, discount grocers, and online subscription services reflects this heightened price sensitivity.
Utilities and energy costs, influenced by global commodity markets and domestic policy, have encouraged households to become more conscious of energy consumption, invest in efficiency upgrades when possible, and consider new technologies such as smart thermostats or home solar installations. Resources from the U.S. Energy Information Administration and Energy Star provide guidance on how energy-efficient appliances and behavioral changes can reduce monthly bills, a topic that aligns closely with USA update's energy coverage.
Healthcare remains a complex and often unpredictable component of household budgets. Studies from the Kaiser Family Foundation and the Commonwealth Fund highlight the burden of out-of-pocket costs, premiums, and deductibles, especially for families without comprehensive employer-sponsored coverage. Under budget pressure, some individuals postpone elective procedures, reduce prescription adherence, or skip preventive care, decisions that can have long-term health and financial consequences.
In this environment, many households are effectively re-drawing the line between essential and discretionary spending, sometimes reclassifying categories such as high-speed internet or mobile data as non-negotiable necessities due to their centrality to work, education, and social life. This evolving hierarchy of needs is one of the most important ways in which budget pressure is reshaping everyday priorities.
Trading Down, Not Opting Out: The Rise of Value-Seeking Behavior
One of the most striking patterns in recent consumer research is that, under budget pressure, households often seek to preserve the experience or function of a purchase while reducing its cost, rather than eliminating the purchase altogether. Economists and market analysts refer to this as "trading down" or "value-seeking" behavior.
In practical terms, this may mean switching from premium brands to store brands, choosing mid-range products instead of top-tier models, or moving from restaurant dining to takeout and home cooking while still seeking moments of indulgence. Reports from McKinsey & Company, Deloitte, and PwC have documented how this behavior has reshaped sectors such as consumer packaged goods, apparel, and quick-service restaurants. Discount retailers, off-price chains, and warehouse clubs have gained market share, while many mainstream retailers have expanded their private-label offerings and promotional strategies.
Online shopping has amplified this trend by making price comparison and product research easier than ever. Platforms such as Amazon, Walmart, and Target have invested heavily in recommendation engines, subscription services, and loyalty programs that emphasize value and convenience. Independent price-tracking tools and review sites further empower consumers to seek the best deal, turning budget pressure into a catalyst for more informed decision-making.
At the same time, there is evidence from sources like NielsenIQ and Statista that consumers are still willing to pay a premium in certain categories that they view as central to their identity or well-being, such as health and wellness, children's needs, or specific hobbies. In these cases, households may cut back more sharply in other areas to preserve spending where it feels most meaningful. This reallocation of discretionary funds reflects not just financial constraints but also a deliberate expression of values and priorities.
For our loyal fans this shift toward value-seeking has implications across multiple coverage areas, from consumer behavior and business strategy to employment trends, as companies adjust product lines, pricing, and workforce needs to align with more cost-conscious customers.
Interactive Budget Pressure Planner
Move the slider to set how tight your budget feels, then adjust your spending mix. See how essentials, savings, and discretionary choices shift.
Debt, Credit, and the Psychology of Financial Stress
As living costs rise and savings buffers are depleted, many households turn to credit to bridge the gap between income and expenses. Data from the Federal Reserve Bank of New York's Household Debt and Credit Report show that credit card balances, auto loans, and other forms of consumer debt have increased in recent years, with delinquency rates edging up in certain segments. Higher interest rates have made carrying balances more expensive, intensifying the burden on those who rely on revolving credit.
The psychological impact of this shift is significant. Research from the American Psychological Association and academic studies published in journals such as the Journal of Consumer Research have found that financial stress can lead to anxiety, impaired decision-making, and even physical health problems. Under pressure, individuals may oscillate between hyper-vigilant budgeting and avoidance behaviors, such as ignoring bills or delaying engagement with financial realities. This can create a vicious cycle in which short-term relief leads to long-term strain.
However, there is also evidence of growing financial literacy and proactive behavior. Nonprofit organizations like the National Foundation for Credit Counseling and government resources such as the Consumer Financial Protection Bureau provide tools for budgeting, debt management, and credit counseling. Many banks and fintech companies now offer digital dashboards, alerts, and educational content designed to help customers track spending, understand interest charges, and build healthier financial habits.
Households that respond to budget pressure by confronting their debt, negotiating with creditors when appropriate, and developing realistic repayment plans are often able to regain a sense of control. For those navigating these challenges, our key finance section at usa-update.com/finance and employment coverage can be useful companions, connecting personal financial strategies to broader trends in wages, benefits, and job opportunities.
Savings, Emergency Funds, and the New Caution
One of the most important lessons many families drew from the pandemic era and subsequent inflationary period is the value of financial resilience. At the same time, sustained budget pressure has made it harder for households to save, especially those in lower and middle income brackets. Surveys from the Federal Reserve, Bankrate, and the Pew Research Center indicate that a significant share of Americans would struggle to cover an unexpected expense of several hundred dollars without borrowing or selling something.
Emergency savings, once a theoretical ideal for many, have become a central goal, even if progress is slow. Financial educators and planners often recommend building a fund that can cover three to six months of essential expenses, but under current conditions, many households focus first on more modest milestones, such as accumulating a few hundred or a few thousand dollars as a buffer against car repairs, medical bills, or temporary income disruptions.
The tension between saving and debt repayment is a recurring theme in personal finance. Some experts, including those at Fidelity Investments and Vanguard, suggest a balanced approach: maintaining at least a small emergency fund while steadily paying down high-interest debt. Others argue for an initial focus on debt if interest rates are particularly punitive. There is no one-size-fits-all answer, and the best strategy depends on individual circumstances, risk tolerance, and employment stability.
Budget pressure tends to make households more cautious about long-term commitments such as major home renovations, new car purchases, or large discretionary travel. Yet it can also motivate a more disciplined approach to saving for retirement, education, or homeownership, particularly when individuals recognize that future security may depend more heavily on personal preparation than on external guarantees. Readers who wish to follow developments in retirement policy, workplace benefits, and household saving behavior can explore related coverage in the economy and finance pages at usa-update.com/economy and usa-update.com/finance.
Employment, Side Gigs, and the Search for Income Flexibility
When expenses rise faster than wages, many households respond not only by cutting spending but also by seeking additional income. The growth of the gig economy, remote work opportunities, and digital platforms has expanded the range of options available, from freelance professional services and online tutoring to ride-hailing, food delivery, and e-commerce micro-businesses.
Studies from the U.S. Bureau of Labor Statistics, the Upwork Freelance Forward report, and research centers such as the Brookings Institution suggest that a substantial and growing share of workers in the United States and other advanced economies engage in some form of supplemental or independent work. For some, this is a primary career path; for others, it is a way to smooth income volatility, pay down debt, or fund specific goals such as education or home purchases.
Budget pressure can accelerate this trend by making additional income feel less optional and more necessary. At the same time, the expansion of flexible work raises questions about benefits, job security, and regulatory frameworks, daily topic that we often explore in the jobs, employment, and regulation areas. Policymakers in the United States, Europe, and other regions continue to debate how best to classify and protect gig workers, balance innovation with worker rights, and ensure that social safety nets keep pace with evolving employment models.
The search for income flexibility also intersects with lifelong learning and reskilling. Under budget pressure, some individuals invest in education or training that can lead to higher-paying roles, often in fields such as technology, healthcare, or skilled trades where demand remains strong. Resources from the U.S. Department of Labor, community colleges, and online education platforms help workers identify in-demand skills and pathways to advancement. For those considering such transitions, following labor market trends through the jobs and technology pages at usa-update.com/jobs and usa-update.com/technology can provide valuable context.
Technology as Both Cost and Cost-Saver
Digital technology occupies a paradoxical place in modern household budgets. On one hand, subscription services, data plans, streaming platforms, and connected devices represent recurring costs that did not exist in previous generations. On the other hand, technology offers powerful tools for saving money, managing finances, and accessing opportunities that can improve long-term financial health.
Under budget pressure, many households are reassessing their technology and entertainment subscriptions, often consolidating streaming services, downgrading plans, or rotating subscriptions month-to-month to follow specific shows or sports seasons. Industry analyses from firms like Deloitte and KPMG note that subscription fatigue is real, and consumers have become more deliberate about which platforms genuinely add value.
At the same time, budgeting apps, digital banks, and personal finance platforms have made it easier to track spending in real time, categorize expenses, and set savings goals. Tools from companies such as Intuit (Mint and Credit Karma), YNAB (You Need A Budget), and various neobanks provide dashboards that translate raw transactions into actionable insights. Educational resources from the Consumer Financial Protection Bureau and nonprofit organizations help users interpret this data and build sustainable plans.
E-commerce and price comparison tools further support cost-conscious behavior. Consumers can quickly compare prices across retailers, read reviews, and use browser extensions that automatically apply coupons or track price history. For larger purchases such as appliances, electronics, or furniture, this transparency can lead to substantial savings.
Technology also enables remote work and online education, which can reduce commuting costs, childcare expenses, or relocation pressures for some households, although it may increase others, such as home energy use or the need for dedicated workspace. The net effect varies widely depending on individual circumstances, but the overarching trend is that digital tools are increasingly central to how households navigate budget constraints. Followers here interested in the intersection of technology, consumer behavior, and work can explore related stories at the updated technology hub at usa-update.com/technology.
Experiences, Travel, and the Redefinition of Leisure
Leisure and travel are often among the first categories scrutinized when budgets tighten, yet research suggests that many households are reluctant to give up experiences entirely. Instead, they tend to modify how, how often, and how luxuriously they engage in travel, entertainment, and lifestyle activities.
After pandemic-related restrictions eased, there was a strong rebound in travel demand, documented by organizations such as the U.S. Travel Association, IATA, and major hospitality companies. Even as budget pressure intensified, many consumers continued to prioritize at least some travel, often opting for shorter trips, off-peak seasons, or destinations closer to home. The rise of "staycations," road trips, and budget-friendly experiences reflects a desire to preserve the restorative and social benefits of leisure while adapting to financial realities.
Entertainment spending has followed a similar pattern. Households may reduce frequency of outings to restaurants, concerts, or cinemas, but still seek occasional special events that feel memorable. At the same time, home-based entertainment, from streaming to gaming to home cooking and hosting, has become more central. Reports from Nielsen and Statista indicate that time spent on at-home activities remains elevated compared with pre-pandemic norms, even as public venues have reopened.
These shifts have implications for sectors covered by our entertainment and lifestyle sections at usa-update.com/entertainment and usa-update.com/lifestyle, as businesses innovate with tiered pricing, loyalty programs, and hybrid offerings that blend in-person and digital experiences. For households, the key theme is not the elimination of joy or relaxation, but a more intentional and value-oriented approach to how those experiences are chosen and funded.
Regional and Global Perspectives: Different Pressures, Similar Patterns
While this article focuses primarily on the United States, similar dynamics are unfolding across North America, Europe, and other regions of interest to USA update readers. In Canada, for example, reports from Statistics Canada and the Bank of Canada highlight the impact of elevated housing costs and interest rates on household budgets, leading to increased caution in discretionary spending. In the United Kingdom and the euro area, analyses from the Bank of England, the European Central Bank, and national statistical offices show that energy prices and food inflation have been particularly salient, prompting governments to implement various support measures and households to adopt energy-saving behaviors.
In emerging markets such as Brazil, South Africa, and parts of Asia, budget pressures intersect with different structural factors, including informal labor markets, currency volatility, and varying levels of social protection. Organizations like the World Bank and OECD document how lower-income households in these regions may face even sharper trade-offs between essentials and discretionary spending, with implications for nutrition, education, and long-term development.
Despite these differences, several common patterns emerge: a reassertion of essentials at the top of spending hierarchies, an emphasis on value and price comparison, increased use of digital tools, and a search for additional income sources. For readers tracking international developments, USA update's original global coverage at usa-update.com/international offers context on how these trends play out across countries and what they mean for trade, investment, and geopolitical dynamics.
Policy, Regulation, and the Role of Institutions
Household budget pressure is not solely a private matter; it is also a policy challenge. Governments, central banks, and regulatory bodies influence the environment in which households make financial decisions through monetary policy, fiscal measures, consumer protections, and social programs. In the United States, debates continue over the appropriate balance between fighting inflation, supporting growth, and protecting vulnerable households from the sharpest edges of economic volatility.
The Federal Reserve's interest rate decisions, documented in its monetary policy statements, directly affect borrowing costs and, indirectly, employment and wage growth. Fiscal policies, including tax credits, subsidies, and targeted relief programs, can either ease or exacerbate budget pressure depending on their design and implementation. Regulatory agencies such as the Consumer Financial Protection Bureau and the Federal Trade Commission play a role in ensuring that financial products, credit terms, and marketing practices are fair and transparent.
Consumer protection regulations, from disclosure requirements on credit cards and loans to rules governing debt collection and data privacy, aim to prevent households from being trapped in exploitative arrangements. At the same time, policymakers must balance these protections with the need to foster innovation and access to credit. This tension is evident in ongoing discussions about fintech regulation, buy-now-pay-later services, and the classification of gig workers.
For subscribing email members or online visiting readers of USA update, understanding these policy dynamics is crucial, as they shape not only individual budgets but also the broader economic landscape. The platform's independent regulation and impartial news sections provide continuing coverage of legislative developments, regulatory actions, and political debates that influence the cost of living, job markets, and consumer rights.
Positive Adaptation: Resilience, Innovation, and Community Support
While budget pressure often brings hardship and anxiety, it also reveals and strengthens forms of resilience that might otherwise remain latent. Households, businesses, and communities across the United States and beyond are responding with creativity, solidarity, and a renewed focus on long-term sustainability.
On the household level, many families are using this period to build more intentional financial habits, from detailed budgeting and meal planning to conscious consumption and goal-oriented saving. Educational resources from organizations such as Jump$tart Coalition for Personal Financial Literacy, university extension programs, and community nonprofits help individuals develop skills that will serve them well even when economic conditions improve.
Businesses, especially small and medium-sized enterprises, are innovating in response to changing consumer priorities. Some are introducing more affordable product lines, flexible payment options, or subscription models that emphasize value and transparency. Others are investing in efficiency, automation, and digital tools to keep prices competitive without sacrificing quality or worker well-being. Industry associations and research groups like the National Retail Federation and Harvard Business Review document how companies that listen closely to customers, communicate clearly, and act with integrity often emerge stronger from periods of economic strain.
Community organizations, faith groups, and local governments are also playing a role, from food banks and mutual aid networks to financial counseling programs and workforce development initiatives. These efforts can provide immediate relief while also fostering social cohesion and shared purpose. For readers who want to stay informed about such initiatives and how they intersect with broader economic and social trends, the new events and dynamic lifestyle coverage at usa-update.com/events and usa-update.com/lifestyle offer stories of local impact and personal resilience.
Going Onwards = How Budget Pressure May Shape the Future
The way households respond to budget pressure today will influence economic and social outcomes for years to come. If families are able to use this period to develop stronger financial habits, invest in education and skills, and advocate for fair and effective policies, the long-term result could be a more resilient and inclusive economy. If, instead, prolonged strain erodes savings, increases debt, and exacerbates inequality, the consequences could be more challenging.
Several trends merit close attention. First, the evolution of work-through automation, artificial intelligence, remote collaboration, and shifting industry structures-will determine the trajectory of wages, job security, and income distribution. Second, housing affordability, influenced by zoning policies, construction costs, and demographic shifts, will remain central to household budgets and mobility. Third, the path of inflation and interest rates, shaped by global supply chains, energy transitions, and policy choices, will continue to affect the balance between income and expenses.
In this complex environment, trusted information sources play an essential role. The team here is committed to providing readers with clear, evidence-based unique reporting and analysis across its economy, business, finance, jobs, and consumer coverage, connecting high-level trends to the realities of household decision-making. By following developments across the United States, North America, and key international regions, the platform aims to support informed choices, constructive dialogue, and a shared understanding of the forces shaping everyday life.
As households continue to navigate budget pressure, their changing spending priorities tell a story not only of constraint but also of adaptation, creativity, and hope. The choices made in grocery aisles, online carts, job searches, and community meetings collectively shape the direction of the economy and the character of society. In documenting these changes and highlighting the positive responses emerging from them, USA update affirms that even in challenging times, informed and purposeful action can lead to more secure and fulfilling futures.
